This article presents the key macroeconomic indicators of Ukraine and the global economy as of the end of July 2026. The analysis is based on data from the State Statistics Service of Ukraine, the National Bank of Ukraine, the Ministry of Finance, the State Customs Service, the International Monetary Fund, Eurostat, BEA, BLS, the US Federal Reserve, the European Central Bank, ONS, NBS, TurkStat, IBGE, and other official institutions. For indicators relating to July and the second quarter, statistical data published after the end of the reporting period were also used.
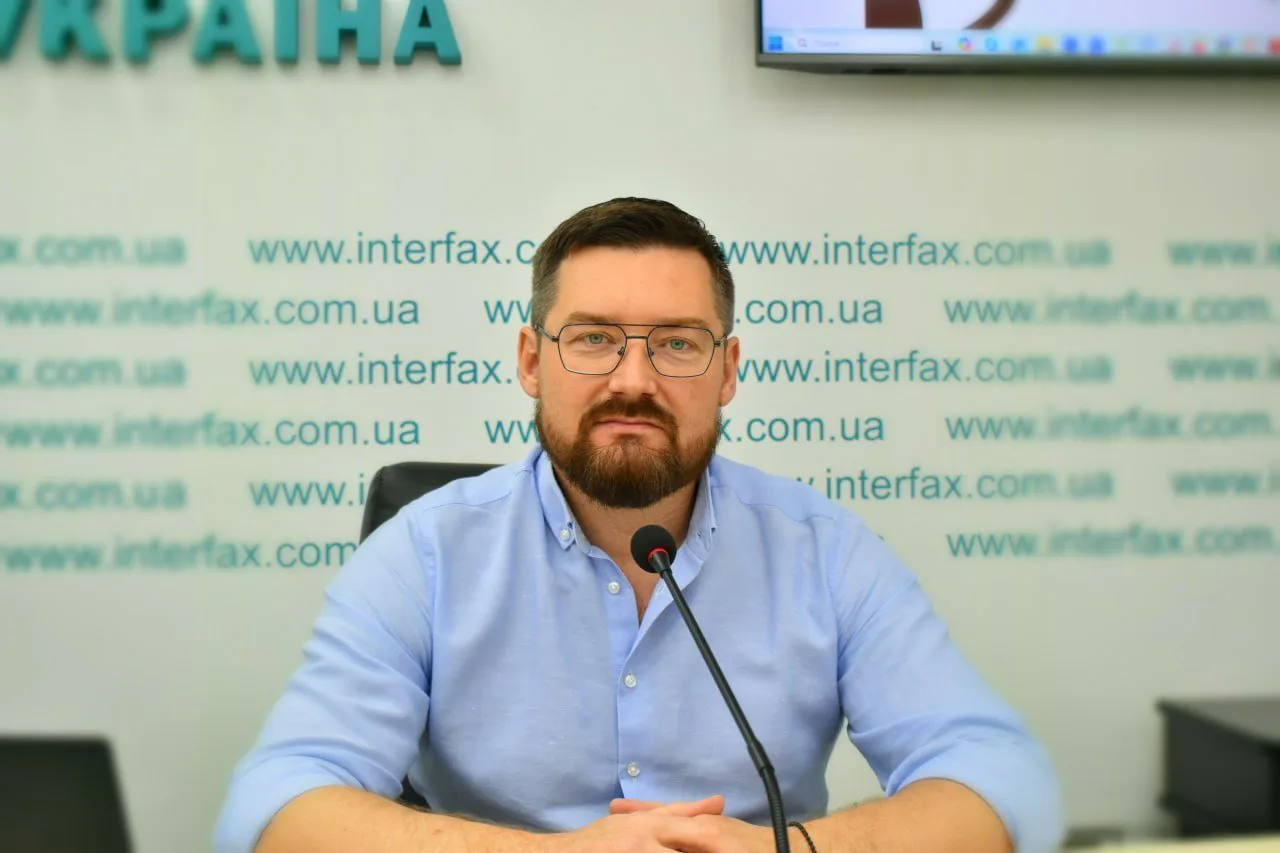
Maksym Urakin, Director of Development and Marketing at Interfax-Ukraine, PhD in Economics, and founder of the Experts Club information and analytical center, presented an overview of the main trends that shaped the Ukrainian and global economies over the first seven months of 2026.
Macroeconomic Indicators of Ukraine
As of the end of July 2026, the Ukrainian economy maintained relative macrofinancial stability amid the full-scale war, but the pace of economic recovery remained slow. After contracting at the beginning of the year, real GDP returned to weak growth, but inflationary risks intensified, prompting the National Bank to raise its key policy rate for the first time in several months. International reserves remained near $51.2 billion after a sharp increase in June, while the merchandise trade deficit for January–July grew to approximately $34 billion.
The main features of the economic situation were high defense spending, the budget's dependence on international financing, a further increase in imports, labor shortages, and substantial business costs for energy and logistics. At the same time, continued financial support from partners, business adaptability, and the gradual recovery of agricultural production created conditions for a revival of economic activity in the second half of the year.
According to the preliminary estimate of the State Statistics Service of Ukraine, real GDP increased by 0.4% in the second quarter of 2026 compared with the same quarter of 2025. Compared with the previous quarter, adjusted for seasonal factors, the economy grew by 0.3%. Nominal GDP amounted to UAH 2,305.7 billion. These data were released on September 9, after the end of the reporting period.
Thus, following a year-on-year contraction of 0.6% in the first quarter, the Ukrainian economy returned to positive dynamics. However, growth of less than half a percent effectively meant remaining close to stagnation, while the recovery was uneven across individual sectors.
On July 30, the National Bank revised its forecast for Ukraine's real GDP growth in 2026 from 1.3% to 1.8%. The regulator expected an easing of fiscal policy, localization of defense production, and larger harvests to support economic activity in the second half of the year. Economic growth was forecast to accelerate to approximately 2.8–3% annually in 2027–2028.
At the same time, the NBU noted that the destruction of production facilities, energy installations, and logistics infrastructure continued to restrain domestic production. A shortage of skilled workers, security risks, and insufficient private-sector investment activity also remained important constraints.
The inflation situation deteriorated in July compared with June. According to the State Statistics Service, consumer prices rose by 0.3% over the month after falling by 0.1% in June. Annual inflation accelerated from 7.2% to 7.7%. Compared with December 2025, consumer prices increased by 6.0%.
Core inflation in July stood at 8.1% year on year, remaining at June's level. On a monthly basis, core prices increased by 0.3%, compared with 0.5% in the previous month. Thus, headline inflation accelerated, but underlying price pressure remained relatively stable, although it exceeded the overall consumer price index.
According to the National Bank, prices for raw food products in July were 2.2% higher than a year earlier. Price growth for processed food products slowed to 10%, while services inflation remained high at 13.7%. Price increases for certain transport services and housing rentals accelerated.
Administratively regulated prices rose by 11.8% year on year. Their dynamics were affected by increases in water supply, wastewater treatment, and public transport tariffs in a number of cities. Meanwhile, annual fuel price growth slowed to 28.0% from 33.4% in June, although gasoline and diesel fuel started becoming more expensive again in the second half of July due to changes in global oil prices.
The main drivers of inflationary pressure remained companies' expenditures on energy resources, wages, and logistics. Additional pressure came from infrastructure damage, labor shortages, and the need to finance backup sources of electricity supply.
The NBU also envisaged the possibility of a further increase in its key policy rate to 16% in the fourth quarter of 2026. A return to the cycle of monetary policy easing was expected no earlier than the second quarter of 2027, provided inflationary pressure declined.
“July showed that Ukrainian inflation remains primarily a problem of high production costs. Even with relatively moderate monthly price increases, core inflation exceeds 8%, services are becoming almost 14% more expensive, and fuel has risen by more than a quarter over the year. Raising the key policy rate to 15.5% should curb secondary inflationary effects and support hryvnia savings, but a long-term reduction in inflation is impossible without stabilizing energy, logistics, and production costs,” Urakin emphasized.
The foreign exchange sector demonstrated relative stability after the substantial increase in reserves in June. According to preliminary NBU data, Ukraine's international reserves stood at $51.199 billion as of August 1, 2026, having decreased by $70.4 million, or 0.1%, during July.
Thus, after reserves increased by 12.1% in June to $51.269 billion, their level remained virtually unchanged in July. At the same time, the pattern of fund flows indicated that significant demand for foreign currency persisted.
During July, the National Bank sold about $4.76 billion on the foreign exchange market. At the same time, approximately $1.64 billion was credited to the government's foreign currency accounts with the NBU, including $683.3 million from the International Monetary Fund, $498.7 million through World Bank accounts, and $458.6 million from placements of foreign currency-denominated domestic government bonds.
Reserve dynamics were also affected by government debt payments, the government's conversion of foreign currency receipts obtained under external financing, and revaluation of reserve assets. Net international reserves fell by approximately $669 million, or 1.8%, in July to $36.3 billion. Total international reserves covered approximately 4.2 months of future imports.
In its July macroeconomic forecast, the NBU raised its expected volume of international reserves at the end of 2026 to $69.7 billion. Reserves were forecast at $73.7 billion at the end of 2027 and approximately $70 billion at the end of 2028. Achieving these figures depended on the timely receipt of large-scale international financial support.
“Maintaining international reserves near $51 billion is an important stabilizing factor for the foreign exchange market. However, the National Bank's sale of almost $4.8 billion in a single month shows that the structural shortage of foreign currency remains substantial. Ukraine has an adequate stock of external liquidity for current stabilization, but without increasing exports of goods and services, this resource cannot become the foundation of long-term economic development,” Urakin believes.
Foreign trade remained one of the principal sources of macroeconomic imbalances. According to the State Customs Service of Ukraine, merchandise turnover in January–July 2026 amounted to $82.2 billion. Goods imports reached $58.1 billion, while exports totaled $24.1 billion. Thus, the merchandise trade deficit over seven months amounted to about $34 billion. Compared with the first-half results, when the deficit was approximately $28.3 billion, it increased by $5.7 billion. Imports exceeded exports by approximately 2.41 times.
In July alone, imports increased by approximately $8.8 billion, while exports rose by only $3.1 billion. These dynamics showed that the Ukrainian economy remained highly dependent on imports amid the war.
China remained the largest supplier of goods to Ukraine, with $16.8 billion worth of products imported from it in January–July. China's share of total merchandise imports was about 28.9%. The next trading partners were Poland, at $5.5 billion, and Germany, at $3.8 billion.
The main destinations for Ukrainian exports remained Poland, which received $2.8 billion worth of goods, Türkiye at $2 billion, and Germany at $1.5 billion.
Machinery, equipment, and vehicles accounted for the largest share of imports, at $25.7 billion. Fuel and energy products worth $8.5 billion and chemical industry products worth $8 billion were imported. Together, these three categories accounted for about 73% of total merchandise imports.
The high share of machinery and equipment reflected the needs of the defense industry, energy, transport, and investment projects. At the same time, the import structure also demonstrated the insufficient development of domestic production of certain industrial products and components.
Food products formed the basis of Ukrainian merchandise exports, totaling $14.1 billion, or about 58.5% of all exports. Metals and metal products accounted for $2.5 billion, while machinery, equipment, and transport accounted for $2.1 billion.
This structure confirmed Ukraine's continued high dependence on agricultural and raw-material exports. The share of high-value-added products remained insufficient to compensate for the rapid growth in import needs.
“The $34 billion merchandise trade deficit over seven months is one of the key structural challenges for the Ukrainian economy. A significant portion of imports is necessary for defense, energy, and infrastructure reconstruction. At the same time, equipment imports must be transformed into new production capacities, increased productivity, and export development. Without this, the trade gap will continue to be financed mainly through international aid,” Urakin stressed.
The budget situation in July remained tense but manageable thanks to large-scale external financing. According to operational data from the Ministry of Finance, UAH 2.06 trillion was received by the general fund of the state budget in January–July 2026.
Total receipts to the general and special funds of the state budget amounted to about UAH 3.25 trillion. Cash expenditures of the state budget reached UAH 3.43 trillion over seven months, of which general fund expenditures amounted to UAH 2.58 trillion.
In July alone, UAH 165.8 billion was received by the general fund, while cash expenditures from the general fund amounted to UAH 345.9 billion.
International grant assistance credited to the general fund of the state budget in January–July amounted to UAH 569.6 billion. Another UAH 146.1 billion came from the transfer of part of the National Bank of Ukraine's profits. Thus, international support and special revenues remained important components of budget resilience.
Security and defense remained the main area of budget spending. Over seven months, UAH 1.63 trillion, or 63.2% of total general fund expenditures, was allocated to these needs. In July, the relevant expenditures amounted to UAH 222.5 billion.
In January–July, UAH 993.5 billion was allocated to wages and associated charges for public-sector employees, UAH 424.9 billion to subsidies and current transfers to enterprises, and UAH 410.9 billion to social security. Expenditures on goods and services amounted to UAH 319 billion.
Government debt servicing cost UAH 200.7 billion, and transfers to local budgets amounted to UAH 162.4 billion.
Actual government borrowing into the general fund of the state budget over seven months amounted to UAH 607.9 billion. UAH 299.4 billion was raised from domestic sources and UAH 308.5 billion from external sources. Government debt repayments during this period amounted to UAH 335.5 billion.
On July 1, 2026, changes to budget legislation took effect, under which receipts from the military levy are directed to a special fund of the state budget for the remuneration of service members of the Armed Forces of Ukraine. In July, UAH 17.9 billion in military levy receipts entered this fund.
As of July 31, Ukraine's state and state-guaranteed debt amounted to UAH 9.572 trillion, or approximately $214.18 billion. Its volume increased by UAH 81.3 billion over the month.
External liabilities made up the bulk of the debt portfolio. External state debt amounted to UAH 7.3 trillion, domestic debt to UAH 2.01 trillion, and state-guaranteed debt to UAH 261.1 billion.
The predominantly concessional structure of government borrowing remained a positive factor. About 64.4% of the debt portfolio consisted of financing from international financial organizations and foreign governments. The weighted average interest rate on state debt fell to 4.40% at the end of July, and the weighted average time to maturity was 13.06 years.
“Ukraine's budget model remains wartime in its structure. More than 63% of general fund expenditures are directed toward security and defense, while civilian programs depend heavily on international financing. At the same time, the growth of public debt is not in itself the main risk if financing remains long-term and concessional. The key question is whether budget expenditures and external aid create conditions for increasing future economic potential,” Maksym Urakin noted.
The labor market situation remained mixed. On the one hand, employers continued to report shortages of skilled workers, especially in industry, construction, logistics, and technical occupations. On the other hand, structural unemployment remained significant due to geographical imbalances, forced migration, and mismatches between workers' professional skills and employers' needs.
According to the State Statistics Service, the average nominal wage of a full-time employee in July 2026 was UAH 32,243. Compared with July 2025, it increased by 21.7%, but fell by 1.6% relative to June 2026.
Nominal wage growth considerably exceeded annual consumer inflation. This indicated an increase in real pay in the sector covered by the statistics, although the overall income situation of the population remained uneven.
In its July forecast, the National Bank expected the overall unemployment rate to fall to approximately 10% by the end of 2026 and to about 9% in 2027–2028. At the same time, real wages were forecast to increase by more than 12% in 2026.
In the agricultural sector, July was a period of noticeable improvement in production indicators. According to the State Statistics Service, agricultural output in January–July 2026 increased by 17.2% compared with the same period of the previous year.
This was a substantial change compared with the first half, when agricultural output contracted by 1.6%. The positive dynamics were primarily driven by the arrival of the new harvest and increased crop production. At the same time, shifting harvest schedules, weather conditions, and a low comparison base had a significant impact on the agricultural sector's results. Therefore, the sharp acceleration of production in July should not automatically be interpreted as a long-term increase in the sector's productivity. Agriculture remained a key source of merchandise exports, foreign currency earnings, and food security. However, increasing its economic impact still required investment in agricultural processing, product storage, transport infrastructure, and logistics.
Global Economy
The global economy remained relatively resilient at the end of July 2026, although its development was accompanied by high geopolitical uncertainty, energy risks, and uneven inflation dynamics. The conflict in the Middle East continued to affect energy markets, while investment in artificial intelligence, digital technologies, and industrial automation supported economic activity in a number of leading countries.
In the July update of the World Economic Outlook, released on July 8, the International Monetary Fund forecast global economic growth of 3.0% in 2026 and 3.4% in 2027.
Compared with its April estimates, the forecast envisaged somewhat weaker economic dynamics in the current year but a faster recovery in the next. The IMF stressed that the global economy was affected by two opposing forces: a negative energy shock caused by war and a positive technological impetus associated with the development of artificial intelligence.
Global disinflation, which had been under way since 2024, effectively came to a halt. The IMF raised its forecast for global inflation in 2026 to 4.7%. The main risks remained further escalation of armed conflicts, intensifying trade disputes, deteriorating financial conditions, and increasing public debt.
At the same time, technological investment created additional opportunities for economies integrated into global production chains for semiconductors, electronics, digital equipment, and software solutions.
The US economy continued to grow in the second quarter of 2026, although the pace of economic activity slowed. According to the preliminary estimate by the Bureau of Economic Analysis dated July 30, real US GDP increased at an annualized rate of 1.5%, compared with 2.1% in the first quarter. In conventional quarter-on-quarter terms, growth was approximately 0.4%.
Consumer spending, investment, and exports made the main positive contributions. At the same time, government spending declined and imports increased, negatively affecting the overall result.
A distinctive feature of the economic situation was the growth in private investment in technological areas, particularly data centers, digital infrastructure, and equipment for artificial intelligence.
In July, US consumer inflation slowed. According to the Bureau of Labor Statistics, the CPI increased by 3.4% year on year, compared with 3.5% in June.
On a seasonally adjusted monthly basis, consumer prices rose by only 0.1% after falling by 0.4% in June. Core inflation, excluding food and energy, stood at 2.5% year on year, compared with 2.6% a month earlier.
Energy prices remained 14.7% higher than in July 2025, although the energy index decreased by 1.5% over the month. Food inflation stood at 3.0% year on year.
On July 29, the US Federal Reserve kept its target range for the federal funds rate at 3.50–3.75%. Nine members of the Federal Open Market Committee supported the decision, while three favored raising the rate by 25 basis points.
The Fed noted that economic activity continued to grow at a steady pace and that labor market conditions remained relatively stable. At the same time, inflation was still above the 2% target, limiting the scope for monetary policy easing.
The European economy showed a moderate recovery in the second quarter. According to Eurostat's preliminary flash estimate of July 30, real GDP grew by 0.4% quarter on quarter in the euro area and by 0.5% in the European Union. The corresponding year-on-year rates were 1.0% and 1.2%.
Subsequent revisions published in September raised the quarter-on-quarter growth estimates to 0.6% in the euro area and 0.7% in the European Union. Annual economic growth was revised to 1.2% and 1.4%, respectively.
Thus, the European economy showed improving dynamics, but its growth remained moderate due to high energy costs, trade risks, and structural problems in industry.
According to Eurostat's preliminary estimate of July 31, annual inflation in the euro area increased to 2.9%, compared with 2.8% in June. Final data confirmed this figure. Inflation in the European Union stood at 3.0%.
Higher energy prices were the principal factor behind the acceleration of inflation. According to the preliminary estimate, they rose by 10.0% year on year, compared with 8.5% in June. Services inflation accelerated to 3.3%, and inflation in non-energy industrial goods to 0.9%.
At the same time, price growth for food, alcohol, and tobacco slowed to 1.2%. Core inflation excluding energy, food, alcohol, and tobacco was approximately 2.5%.
On July 23, the European Central Bank left all three key interest rates unchanged. The deposit facility rate stood at 2.25%, the main refinancing operations rate at 2.40%, and the marginal lending facility rate at 2.65%.
The ECB emphasized that further decisions would depend on inflation risks, the impact of the energy shock, and economic dynamics. The regulator also noted that the full impact of higher energy prices had not yet been felt in the European economy.
Inflationary pressure also intensified in the United Kingdom in July. According to the Office for National Statistics, consumer inflation stood at 2.9% year on year, compared with 2.6% in June. Prices rose by 0.3% over the month.
Core inflation remained at 2.6%, while services inflation slowed to 3.4%. Housing and utility services and certain non-food products made the main contributions to the acceleration in the headline figure.
According to the preliminary ONS estimate, real UK GDP increased by 0.4% in the second quarter of 2026 compared with the previous quarter, following growth of 0.6% in the first quarter. The services sector, which grew by 0.5%, made the main contribution. Construction added 0.3%, while industrial production remained unchanged.
On July 30, the Bank of England kept its Bank Rate at 3.75%. Six members of the Monetary Policy Committee supported maintaining the rate, while three favored raising it to 4%.
“July demonstrated that the largest central banks continue to act cautiously. The Federal Reserve and the European Central Bank kept interest rates unchanged, as did the Bank of England. At the same time, inflation in the United States slowed to 3.4%, while it accelerated in the euro area and the United Kingdom. Such divergent dynamics mean that the global cost of capital will remain relatively high, while Ukraine will continue to face risks of imported inflation through energy, equipment, and logistics,” Urakin noted.
China's economy continued to show positive but uneven dynamics. In the first half of 2026, China's real GDP increased by 4.7% year on year. Growth was 5.0% in the first quarter and slowed to 4.3% in the second quarter.
In July, industrial production growth slowed to 4.5% year on year, from 5.3% in June. In January–July, industrial output increased by 5.3%.
High-tech manufacturing showed particularly strong growth, with output increasing by 16.9% year on year in July. Production of computers, communications equipment, and other electronic equipment increased by 19.1%.
These figures confirmed China's continued strong position in global production chains associated with digitalization, electronics, and artificial intelligence.
At the same time, domestic consumer demand remained weak. Retail sales grew by only 0.6% year on year in July and by 1.2% in January–July. Automobile sales fell by 17.0% in July, indicating a difficult situation in part of the consumer market.
According to China's National Bureau of Statistics, consumer inflation in July was just 0.5% year on year, and prices declined by 0.1% over the month. Average CPI growth over seven months was 0.9%.
At the same time, industrial producer prices in July were 3.5% higher than a year earlier. This gap between consumer and producer inflation reflected the significant impact of energy and raw material costs on industry amid relatively weak domestic demand.
India continued to be one of the world's most dynamic major economies. According to the Ministry of Statistics and Programme Implementation of India, real GDP increased by 7.8% year on year in the first quarter of the 2026/27 financial year, that is, April–June 2026.
The main drivers of economic growth remained domestic demand, investment, infrastructure development, industry, and services. Government infrastructure programs and rising private consumption played an important role.
At the same time, inflation in India accelerated in July to 4.45% year on year, compared with 4.38% in June. Food inflation stood at 5.52%, placing additional pressure on the purchasing power of the population.
Despite this, India maintained significantly higher economic growth rates than most other major economies thanks to its large domestic market and favorable demographic structure.
Türkiye continued to operate under conditions of extremely high inflation in July. According to TurkStat, consumer prices rose by 1.78% compared with June, while annual inflation stood at 31.75%, down from 32.11% in the previous month.
Thus, the annual figure continued to decline but remained more than ten times higher than inflation in the euro area. High financing costs, rising business expenses, and declining real purchasing power continued to restrain domestic demand.
Subsequent data for the second quarter showed that Türkiye's real GDP increased by 2.3% year on year and by 1.1% compared with the previous quarter. This indicated continued positive economic dynamics, although high inflation continued to undermine the quality of growth.
Brazil showed more moderate economic dynamics. According to IBGE, real GDP in the second quarter of 2026 increased by approximately 0.5% compared with the previous quarter and by 2.0% year on year.
Economic growth in the first half was about 1.9%. The services sector, domestic consumption, and certain segments of industrial production remained the main drivers of economic activity.
In July, Brazil's IPCA consumer price index rose by just 0.07%, compared with 0.16% in June. Annual inflation slowed from 4.64% to 4.44%, while consumer prices had increased by 3.44% since the beginning of the year.
Slower inflation created conditions for a gradual improvement in financial conditions, although high interest rates and limited budgetary resources remained constraining factors.
“The largest emerging economies are demonstrating increasingly different growth models. China remains a powerful industrial and technological center, but its domestic demand noticeably lags behind production. India is growing at almost 8%, relying on its large domestic market and investment. Türkiye continues to battle inflation above 30%, while Brazil is gradually stabilizing price dynamics. For Ukraine, the experience of economies that achieve long-term growth through the development of industry, technology, and high-value-added products is particularly important,” Urakin believes.
Conclusions
As of the end of July 2026, the Ukrainian economy maintained relative macrofinancial stability, but its structural imbalances continued to intensify.
Real GDP increased by only 0.4% year on year in the second quarter and by 0.3% compared with the previous quarter. The National Bank raised its forecast for economic growth in 2026 to 1.8%, but this figure remained insufficient for a rapid recovery of productive capacity.
Consumer inflation accelerated to 7.7% year on year in July, from 7.2% in June. Core inflation remained at 8.1%, while the National Bank raised its key policy rate to 15.5%. At the same time, the inflation forecast for the end of 2026 was revised upward to 10%.
International reserves stood at $51.2 billion as of August 1, having remained practically unchanged over the month. At the same time, the scale of foreign exchange interventions remained substantial, and foreign exchange market stability continued to depend on the timely receipt of international aid.
The merchandise trade deficit for January–July increased to approximately $34 billion, with imports of $58.1 billion and exports of $24.1 billion. This confirmed Ukraine's continued significant dependence on imported goods, equipment, and energy resources.
Receipts to the general fund of the state budget over seven months amounted to UAH 2.06 trillion, while expenditures reached UAH 2.58 trillion. UAH 1.63 trillion, or 63.2% of general fund expenditures, was allocated to security and defense. International grant assistance amounted to UAH 569.6 billion.
State and state-guaranteed debt reached UAH 9.57 trillion at the end of July. At the same time, the predominance of long-term concessional financing and the reduction in the weighted average cost of debt to 4.40% mitigated debt servicing risks.
Positive factors included growth in average nominal wages, improved agricultural production results, development of defense enterprises, and continued external financing. Negative factors included high dependence on imports, a structural labor shortage, weak industrial production, and insufficient export growth.
The global economy also remained subject to heightened uncertainty. The International Monetary Fund forecast global growth of 3.0% in 2026 and 3.4% in 2027.
The United States grew by approximately 0.4% in conventional quarter-on-quarter terms in the second quarter. According to revised data, GDP in the euro area rose by 0.6% and in the United Kingdom by 0.4%. At the same time, July inflation stood at 3.4% in the United States, 2.9% in the euro area, and 2.9% in the United Kingdom.
China's economy grew by 4.7% in the first half, but industrial production growth slowed to 4.5% year on year in July and retail sales growth to 0.6%. India maintained high GDP growth of 7.8% in April–June, while Türkiye combined positive economic dynamics with inflation of 31.75%. Brazil showed moderate growth amid a slowdown in inflation to 4.44%.
“July 2026 confirmed that the Ukrainian economy is capable of maintaining financial stability even with exceptionally high wartime spending, but this model remains dependent on external resources. Growth in reserves, international grants, and concessional loans makes it possible to finance defense and social obligations, but does not eliminate the main structural problems — the trade balance deficit, insufficient industrial production, and labor shortages,” Urakin noted.
In the view of the Experts Club founder, the main task of economic policy in the coming years should be the transition from a model of wartime stabilization to one of investment- and production-led growth.
“The next stage of economic policy should involve not only maintaining financial stability but also transforming imported equipment, international funds, and defense spending into new productive assets. The foundations of long-term development should be energy autonomy, the defense-industrial complex, agricultural processing, mechanical engineering, localization of production, logistics, digital technologies, and exports of high-value-added products. Ukraine's transition from a wartime stabilization economy to a model of sustainable postwar growth will depend precisely on its ability to implement such a transformation,” Maksym Urakin concluded.
Project Manager of “Economic Monitoring,” PhD in Economics, Maksym Urakin